What's the difference between year-end tax preparation and year-round tax-ready bookkeeping with coordinated filings?
What’s the difference between year-end tax preparation and year-round tax-ready bookkeeping with coordinated filings? Timing, ownership, and financial discipline. Year-end preparation looks backward to assemble information for a tax return. Year-round bookkeeping keeps transactions classified, accounts reconciled, and supporting records organized as the business operates. For founders managing cash, payroll, inventory, and growth decisions, that distinction can determine whether tax season is a controlled handoff or an expensive reconstruction project.
Key Takeaways
- Year-round bookkeeping turns tax season from a frantic data hunt into a simple filing review, giving founders more control over timing and costs.
- Keeping accounts reconciled and transactions classified throughout the year means your financials reflect real business activity, not a scramble to reconstruct the past.
- Coordinated filings between bookkeeping and tax preparation reduce duplicate work and help you avoid missed deductions or filing errors.
- When your bookkeeping is tax-ready all year, you can make growth decisions based on clean numbers instead of waiting for a once-a-year cleanup.
Bookkeeping gives growing companies an operating foundation for cleaner reporting and better coordination with qualified tax partners. Cypher publicly offers outsourced bookkeeping and accounting for growing businesses, including accrual-basis bookkeeping and monthly financial statements in its current public plans.
Year-End Tax Prep vs. Year-Round Bookkeeping: Understanding the Core Difference
The “Shoebox” Approach: Reactive Year-End Tax Preparation
In a reactive model, bank feeds, receipts, payroll records, invoices, payment processor reports, and founder explanations may sit in different places at year-end. A tax preparer must determine which transactions belong in the books, what documentation supports them, and whether the general ledger reflects actual activity. The return may be completed, but the process can require catch-up entries, account reclassifications, missing statements, and prior-period questions.
This can suit a very small business with limited, straightforward activity. It becomes less practical with multiple revenue streams, subscription billing, inventory, contractors, deferred revenue, equity transactions, or more than one entity. Tax preparation reports historical results and calculates filing positions; it does not replace dependable operating records.
The “Financial Command Center” Approach: Proactive Year-Round Tax-Ready Bookkeeping
Tax-ready bookkeeping treats the ledger as an active management system. Transactions are categorized consistently, bank and credit card accounts are reconciled, payroll entries are recorded with appropriate splits, and balance sheet accounts carry forward. Accrual accounting can show revenue, expenses, accounts receivable, accounts payable, and obligations that cash activity alone may obscure.
The purpose is not to make tax decisions outside the tax partner’s role. It is to provide complete, organized, traceable information. Monthly statements, supporting schedules, fixed asset records, inventory detail, and explanations for unusual variances give the tax partner a reliable basis for review and filing preparation.
Why This Distinction Matters for Growing Businesses
Growth adds complexity quickly. New sales channels can create payment processor fees and chargebacks; hiring can create payroll allocation questions; inventory can create receiving, fulfillment, and cost-of-goods-sold issues; and fundraising can add equity and cap-table reconciliation needs. Each can affect reporting, cash visibility, tax support, or all three.
Year-round records let leadership review gross margin, operating expenses, cash runway, collections, vendor obligations, and budget variances before decisions become urgent. The tax partner receives a coherent financial package instead of disconnected documents, while founders can distinguish bookkeeping questions from matters requiring a qualified tax professional.
Cypher’s Role: Your Partner in Tax-Ready Financial Operations
Cypher supports growing companies with outsourced bookkeeping, accounting, CFO services, and financial operations. Its work can include accrual bookkeeping, monthly financial reporting, cash-flow management, forecasting, KPI design, accounts receivable and payable workflows, and tax-ready accounting coordinated with qualified tax partners. The finance team organizes records and reporting; the tax partner applies tax expertise and manages filing responsibilities within its agreed scope.
Key insight: Tax-ready bookkeeping does not replace a tax professional. It provides cleaner inputs, clearer support, and a more efficient review path. For a founder, the practical benefit is one connected financial process instead of year-end scrambling and day-to-day guesswork.
The High Cost of Cleanup: Why Year-End Prep Alone Creates Surprise Fees
The “Cleanup Tax” Angle: Understanding Unexpected CPA Bills
Tax preparation fees become less predictable when records require reconstruction. A tax professional may need to locate documents, rebuild transaction detail, correct account mappings, investigate unexplained balances, and prepare adjusting entries. These tasks differ from reviewing organized books and can expand both the work and final bill.
This “cleanup tax” is not a government charge; it is the operational cost of postponing bookkeeping until filing season. It is especially difficult when the original scope covered tax preparation only. Founders may expect a filing fee, then discover that historical bookkeeping, reconciliation, inventory analysis, or payroll corrections require separate work.
Common Cleanup Triggers: Inventory Errors, Payroll Splits, and Reconciliations
Inventory requires continuity: beginning inventory should agree with the prior period’s ending inventory, while purchases, shrinkage, adjustments, and cost of goods sold need support. A zero ending inventory balance despite ongoing stock can raise questions beyond one journal entry and may require accounting-method guidance from the tax professional.
Payroll requires more than one cash withdrawal. Wages, employer taxes, benefits, reimbursements, and department or entity allocations may need separate journal lines. Missing splits distort gross margin and operating expenses. Unreconciled bank accounts, payment processors, credit cards, merchant fees, and accounts receivable create additional investigation before taxable income can be evaluated.
The Impact of Inaccurate Balance Sheets on Tax Filings
A balance sheet is a continuity record. Cash, receivables, inventory, fixed assets, liabilities, loans, deferred revenue, and equity should make sense at the start and end of each period. Inaccurate accounts can misstate the income statement, leave depreciation schedules incomplete, cause loan balances to differ from lender statements, and place owner or shareholder activity in the wrong account.
Tax filings rely on information connecting across periods. When that connection is missing, the tax partner must determine which figures are reliable and which need correction, delaying preparation and making it harder to separate tax issues from accounting-record issues.
Beyond Dollars: The Time and Stress Burden of Messy Books
Cleanup consumes founder attention during deadlines, customer demands, payroll decisions, and next-year planning. Employees may search old emails, retrieve invoices, explain transfers, or recreate approval histories. Research from Block Advisors and H&R Block reports that integrating bookkeeping and tax preparation efforts increases data accuracy by 40%. Year-round Bookkeeping shifts work toward a repeatable monthly rhythm.
What “Tax-Ready Bookkeeping” Looks Like Month-to-Month
Tax-ready bookkeeping is a recurring process. Each month, the finance team classifies activity, reconciles accounts, updates schedules, and investigates exceptions while transactions remain familiar. This supplies dependable statements and organized information for filing review, connecting the ledger with cash, payroll, inventory, fixed assets, and management decisions.
The Foundation: Accrual Accounting and Chart of Accounts Hygiene
Accrual accounting records revenue when earned and expenses when incurred, subject to company policies. It can improve visibility into accounts receivable, accounts payable, deferred revenue, prepaid expenses, accrued liabilities, and cost of goods sold. A maintained chart of accounts assigns transactions consistently, helping management compare periods and the tax partner understand balances.
Monthly review should identify unusual postings, duplicate vendors, personal expenses, uncategorized transactions, and transfers recorded as revenue or expenses. The aim is a coherent ledger supporting statements, tax information, and internal reporting.
Monthly Financial Reconciliation: The Key to Balance Sheet Continuity
Reconciliation compares records with source documents. Bank and credit card balances should agree with statements, payment processor activity with deposits and fees, and loan balances with lender records. Accounts receivable, accounts payable, inventory, fixed assets, payroll liabilities, and equity accounts also require review according to activity and accounting policies.
Beginning balances should connect to prior closing balances, and new activity should have invoices, bills, receipts, payroll reports, inventory records, or other support. Resolving a variance during the next close is generally easier than reconstructing its origin later.
Tracking Deductible Expenses Proactively
Expense categorization should occur when bills, receipts, card charges, and reimbursements enter the system. The bookkeeping team can flag unclear transactions, separate business and nonbusiness activity, and retain documentation. The tax partner assesses deductibility, tax treatment, elections, and other tax matters. This division keeps the books useful without turning bookkeeping into tax advice.
Managing Payroll Splits and Multi-Entity Transactions
Payroll entries may distinguish wages, employer taxes, benefits, reimbursements, departments, locations, projects, or legal entities. The journal should agree with payroll reports and show how expenses and liabilities were calculated. Multi-entity businesses also need documented intercompany transfers, shared expenses, management fees, loans, and due-to or due-from balances. Unusual arrangements should be escalated rather than guessed.
Ensuring Audit Preparedness in Your Daily Records
Audit preparedness means maintaining a support trail, not claiming that bookkeeping is an audit or attestation service. Source documents, reconciliations, approval records, fixed asset schedules, inventory counts, debt statements, payroll reports, and explanations for material adjustments should follow the company’s document policy. A reviewer should be able to trace a material balance to its support.
- Post and review transactions using consistent account and entity classifications.
- Reconcile bank, card, processor, loan, payroll, and selected balance sheet accounts.
- Update accounts receivable, accounts payable, inventory, fixed asset, and deferred revenue schedules when applicable.
- Document unusual entries, payroll allocations, intercompany activity, and material variances.
- Close the month with financial statements and an open-items list for management review.
- Collect transactions and supporting records.
- Classify activity and post accrual adjustments.
- Reconcile source accounts and investigate variances.
- Update schedules and document exceptions.
- Review monthly statements and preserve the tax support package.
The Coordinated Filing Workflow: Seamless Handoffs with Tax Partners
Coordinated filings work best when responsibilities are defined. The outsourced accounting team maintains books and schedules; the controller or finance lead reviews the close and open questions; and the tax partner applies tax rules, prepares or reviews returns within scope, advises on tax positions, and handles engaged tax communications. This reduces duplicated requests and makes the handoff predictable.
Defining Roles: Bookkeeper vs. Controller vs. Tax Partner/CPA
A bookkeeper records activity, reconciles accounts, supports the monthly close, and maintains documentation. A controller reviews accounting policies, close procedures, reporting, internal controls, and complex accounting matters. A qualified tax CPA or other tax partner determines filing requirements, prepares returns, advises on tax treatment, and may provide IRS representation when separately engaged and authorized.
| Workstream | Outsourced accounting team | Controller or finance lead | Tax partner or CPA |
|---|---|---|---|
| Monthly close | Posts, reconciles, and documents activity | Reviews close quality and exceptions | Uses finalized records for tax analysis |
| Financial statements | Produces monthly reporting | Analyzes trends and policy questions | Reviews relevant tax implications |
| Tax returns | Provides organized schedules and support | Coordinates timing and approvals | Prepares or reviews returns within scope |
| IRS notices | Retrieves ledger and filing support | Coordinates internal response | Advises or represents the company when engaged |
How Cypher Coordinates with Your Tax CPA
Cypher can organize the accounting close, monthly statements, reconciliations, and tax-ready schedules a tax partner needs. Before filing work begins, teams can align on the reporting period, trial balance, chart of accounts, inventory, fixed assets, payroll, equity activity, and open questions. A documented request list gives the tax partner a consistent package rather than requiring the founder to translate between systems.
Cypher provides accounting and financial operations, not tax counsel. Its team coordinates with qualified tax partners so tax judgments remain with the professionals engaged for those services, giving the founder one operating point for financial records while preserving boundaries around tax preparation, advice, and IRS representation.
Quarterly Estimated Taxes and Proactive Tax Planning
Quarterly reporting gives the tax partner earlier visibility into income, deductions, cash balances, owner activity, and performance changes. The tax professional can discuss estimated obligations, filing positions, entity considerations, and planning opportunities; the accounting team can record approved entries and maintain schedules. Estimates depend on current records, tax rules, jurisdiction, entity structure, and advice from the qualified tax partner.
Avoiding IRS Notice Bottlenecks: 1099s, Payroll, and Compliance
Information returns and payroll filings should agree with the ledger, vendor records, payroll reports, and payment data. The accounting team can validate payee information, contractor totals, payroll classifications, and support before deadlines. The tax partner can advise on requirements, forms, deadlines, corrections, and responses.
The IRS has described CP05 notices as reviews that can delay processing while reported income, withholding, or credits are checked. Mismatches involving Forms 1099, wage reporting, or payroll withholding can create questions. Coordinated records do not eliminate notices, but they make source documents and response packages easier to locate.
The Advantage for Growing Companies: Scalability and Specialized Expertise
A coordinated model can mature with transaction volume, headcount, entities, inventory, fundraising, and reporting needs. Founders gain accounting processes, monthly reporting, cash-flow visibility, and tax coordination without assigning every task to one generalist. The tax partner focuses on tax analysis while the accounting team maintains operational records.
Key insight: A seamless tax handoff starts months before filing season. Agree on roles, close books consistently, preserve support, and route tax judgments to the qualified professional responsible for them. This gives leadership better cash-planning information and the tax partner a cleaner basis for compliance work.
Choosing Your Financial Operations Strategy: A Comparative Guide
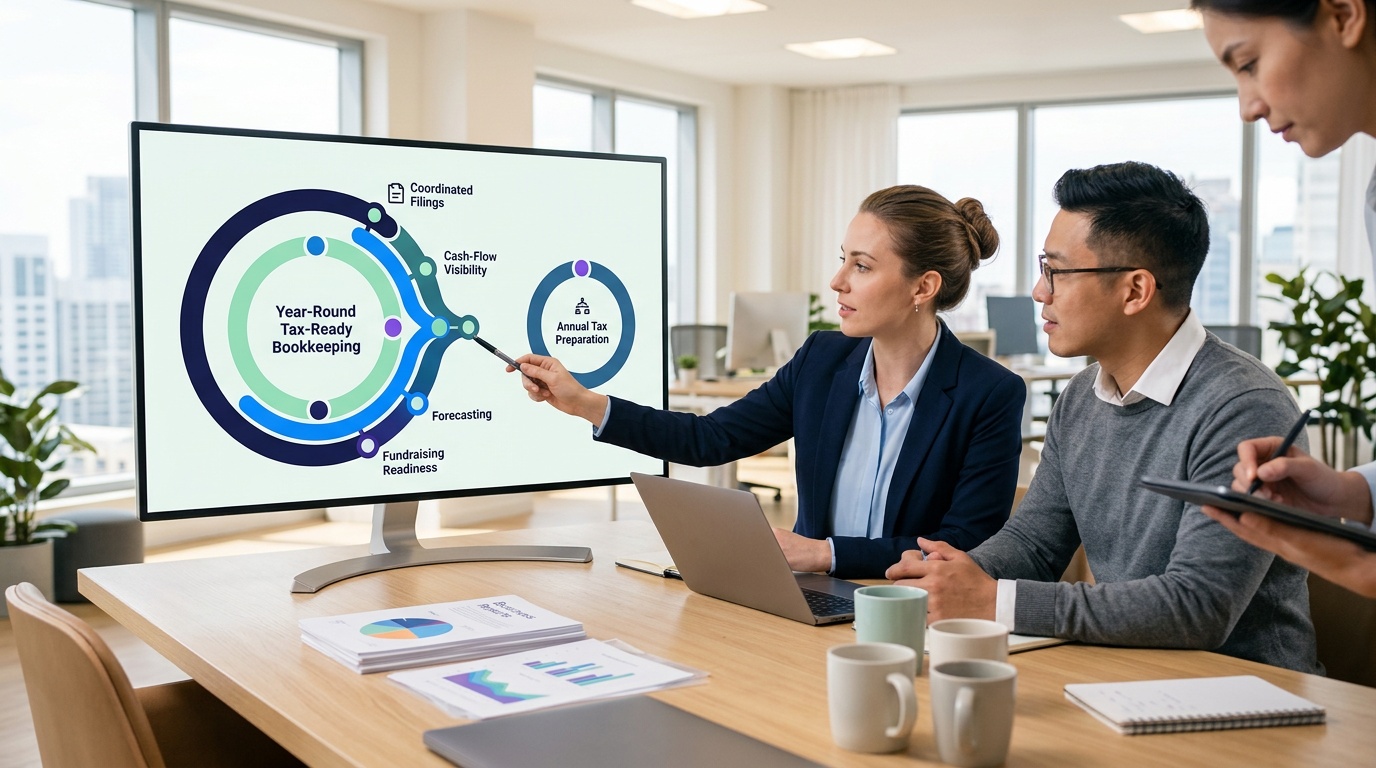
Choosing between annual tax preparation and year-round accounting depends on the finance decision the business needs to support. What’s the difference between year-end tax preparation and year-round tax-ready bookkeeping with coordinated filings? The first concentrates on a historical filing; the second builds financial information throughout the year and routes it to the right tax professional. The choice depends on transaction volume, entity structure, inventory, payroll complexity, reporting needs, and founder involvement.
How We Evaluated Financial Operations Strategies
This comparison uses record quality, financial visibility, predictability of professional work, tax-partner coordination, and scalability. A suitable model should produce supportable statements, preserve balance sheet continuity, and make ownership clear between accounting and tax work. A simple single-owner business may not need the same infrastructure as a SaaS company with deferred revenue, an e-commerce company with inventory, or a group managing several entities.
Option 1: Standalone Year-End Tax Preparation, the Reactive Approach
Best for: a small business with limited transactions, one straightforward entity, minimal payroll complexity, and books maintained throughout the year by the owner or internal team.
Standalone preparation assembles prior-period information, reviews tax documents, and prepares returns within the tax firm’s engagement. It can work when the general ledger, reconciliations, expense records, payroll reports, and schedules are dependable. It is less suitable when the preparer must reconstruct activity, resolve balances, or determine whether entries reflect operations. Founders should request a written scope distinguishing filing work from cleanup, adjustments, notice support, and advisory services.
Option 2: Year-Round Tax-Ready Bookkeeping with Coordinated Filings, the Proactive Approach
Best for: a growing company needing monthly statements, current cash visibility, organized tax support, and a repeatable handoff to a qualified tax partner.
Year-round bookkeeping creates a cadence around coding, reconciliations, accrual entries, payroll allocations, receivables, payables, inventory, fixed assets, and equity. The tax partner receives consistent information rather than disconnected year-end documents. Cypher’s Bookkeeping is positioned for growing businesses needing outsourced accounting support and monthly reporting. The benefit extends to budgeting, forecasting, cash management, board reporting, and fundraising readiness.
Comparison Table: Year-End Tax Prep vs. Year-Round Tax-Ready Bookkeeping
| Criteria | Standalone year-end tax preparation | Year-round tax-ready bookkeeping with coordinated filings |
|---|---|---|
| Primary purpose | Complete historical tax reporting | Maintain current records and support coordinated compliance work |
| Financial visibility | Often concentrated around filing season | Monthly statements, reconciliations, and management reporting |
| Cleanup exposure | Higher when records are incomplete or inconsistent | Exceptions are identified during recurring closes |
| Tax handoff | Documents may arrive as a year-end batch | Schedules, ledgers, and support are prepared throughout the year |
| Growth fit | Best for simple, stable operations | Better suited to changing revenue, payroll, inventory, or entity needs |
When to Consider Each Approach, and When to Evolve
Choose standalone preparation when books are accurate, reconciled, documented, and unlikely to change materially before filing. Move toward year-round work when monthly reporting takes too long, the balance sheet contains unresolved accounts, tax requests disrupt the team, or leadership needs dependable cash and performance information. New payroll, inventory, outside investment, subscription revenue, multiple entities, or a growing contractor base can justify a structured process.
What’s the difference between year-end tax preparation and year-round tax-ready bookkeeping with coordinated filings? It is the difference between purchasing a filing event and building financial operating discipline. For a growth-oriented company, the proactive model connects accounting accuracy, decision support, and tax coordination without assigning tax-specific responsibilities to the bookkeeping team.
Frequently Asked Questions
What are the differences between tax preparation and bookkeeping?
Year-end tax preparation uses historical financial information to prepare tax filings, while bookkeeping maintains and organizes financial records throughout the year. Year-round bookkeeping includes transaction classification, account reconciliations, payroll entries, and supporting schedules. Clean monthly records give a qualified tax partner a more reliable starting point for reviewing and preparing filings.
Is fiscal year end the same as tax year end?
A fiscal year end is the close of a business’s chosen 12-month accounting period, while a tax year end is the period used for tax reporting and may follow different rules. Businesses should confirm the applicable tax year with a qualified tax professional. Bookkeeping should consistently track activity across the selected reporting periods.
Do bookkeepers work with tax preparers?
Bookkeepers can work with tax preparers by organizing financial records, preparing reconciliations, and providing schedules that support tax review. Bookkeepers maintain accounting information, while qualified tax professionals apply tax expertise and manage filing responsibilities within their agreed scope. Coordinated workflows reduce document chasing and make questions easier to resolve.
When should a growing business move from year-end tax preparation to year-round bookkeeping?
A growing business should consider year-round bookkeeping when it has multiple revenue streams, payroll, inventory, subscription billing, contractors, or more than one entity. Monthly accounting helps leadership review cash, margins, obligations, and budget variances while the business operates. The tax partner then receives organized records instead of a year-end reconstruction project.
What are the red flags of a bad tax preparer?
Red flags of a bad tax preparer include promises of guaranteed tax savings, limited questions about the business, unclear responsibilities, pressure to claim unsupported deductions, and reluctance to explain the filing process. Business owners should confirm credentials, scope, documentation expectations, and communication practices. Organized bookkeeping helps a qualified tax professional review filings with better supporting information.
Can year-round bookkeeping reduce unexpected tax preparation costs?
Year-round bookkeeping can make tax preparation costs more predictable by reducing reconstruction, reclassifications, missing records, and unreconciled accounts. The final fee still depends on the tax professional’s scope, the business’s complexity, and the condition of its records. Clear monthly reporting also helps separate bookkeeping work from tax services.